
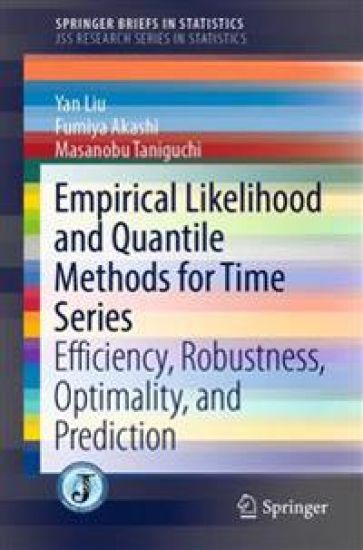
Empirical Likelihood and Quantile Methods for Time Series – hinnat ja saatavuus
Efficiency, Robustness, Optimality, and Prediction
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9789811001512 (nidottu).
Kirjan kuvaus
This book integrates the fundamentals of asymptotic theory of statistical inference for time series under nonstandard settings, e.g., infinite variance processes, not only from the point of view of efficiency but also from that of… Näytä koko kuvaus Piilota kuvaus
This book integrates the fundamentals of asymptotic theory of statistical inference for time series under nonstandard settings, e.g., infinite variance processes, not only from the point of view of efficiency but also from that of robustness and optimality by minimizing prediction error. This is the first book to consider the generalized empirical likelihood applied to time series models in frequency domain and also the estimation motivated by minimizing quantile prediction error without assumption of true model. It provides the reader with a new horizon for understanding the prediction problem that occurs in time series modeling and a contemporary approach of hypothesis testing by the generalized empirical likelihood method. Nonparametric aspects of the methods proposed in this book also satisfactorily address economic and financial problems without imposing redundantly strong restrictions on the model, which has been true until now. Dealing with infinite variance processes makesanalysis of economic and financial data more accurate under the existing results from the demonstrative research. The scope of applications, however, is expected to apply to much broader academic fields. The methods are also sufficiently flexible in that they represent an advanced and unified development of prediction form including multiple-point extrapolation, interpolation, and other incomplete past forecastings. Consequently, they lead readers to a good combination of efficient and robust estimate and test, and discriminate pivotal quantities contained in realistic time series models.
Kirjan tiedot
Vertaa kirjan ”Empirical Likelihood and Quantile Methods for Time Series” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9789811001512.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
Empirical Likelihood and Quantile Methods for Time Series – hintahistoria
Seuraamme kirjan Empirical Likelihood and Quantile Methods for Time Series hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.