
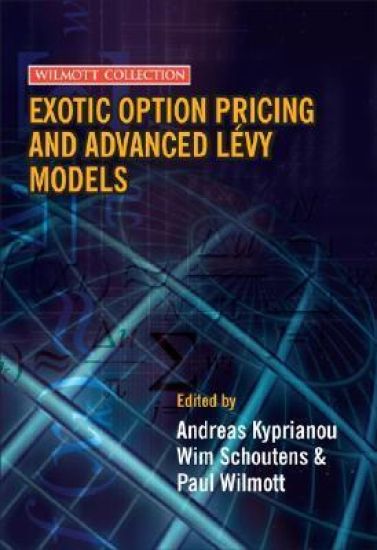
Exotic Option Pricing and Advanced Lévy Models – hinnat ja saatavuus
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9780470016848 (sidottu).
Kirjan kuvaus
Since around the turn of the millennium there has been a general acceptance that one of the more practical improvements one may make in the light of the shortfalls of the classical Black-Scholes model is to replace the underlying source of… Näytä koko kuvaus Piilota kuvaus
Since around the turn of the millennium there has been a general acceptance that one of the more practical improvements one may make in the light of the shortfalls of the classical Black-Scholes model is to replace the underlying source of randomness, a Brownian motion, by a Lévy process. Working with Lévy processes allows one to capture desirable distributional characteristics in the stock returns. In addition, recent work on Lévy processes has led to the understanding of many probabilistic and analytical properties, which make the processes attractive as mathematical tools. At the same time, exotic derivatives are gaining increasing importance as financial instruments and are traded nowadays in large quantities in OTC markets. The current volume is a compendium of chapters, each of which consists of discursive review and recent research on the topic of exotic option pricing and advanced Lévy markets, written by leading scientists in this field. In recent years, Lévy processes have leapt to the fore as a tractable mechanism for modeling asset returns. Exotic option values are especially sensitive to an accurate portrayal of these dynamics. This comprehensive volume provides a valuable service for financial researchers everywhere by assembling key contributions from the world's leading researchers in the field. Peter Carr, Head of Quantitative Finance, Bloomberg LP. This book provides a front-row seat to the hottest new field in modern finance: options pricing in turbulent markets. The old models have failed, as many a professional investor can sadly attest. So many of the brightest minds in mathematical finance across the globe are now in search of new, more accurate models. Here, in one volume, is a comprehensive selection of this cutting-edge research. Richard L. Hudson, former Managing Editor of The Wall Street Journal Europe, and co-author with Benoit B. Mandelbrot of The (Mis)Behaviour of Markets: A Fractal View of Risk, Ruin and Reward
Kirjan tiedot
Vertaa kirjan ”Exotic Option Pricing and Advanced Lévy Models” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9780470016848.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
Exotic Option Pricing and Advanced Lévy Models – hintahistoria
Seuraamme kirjan Exotic Option Pricing and Advanced Lévy Models hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.