
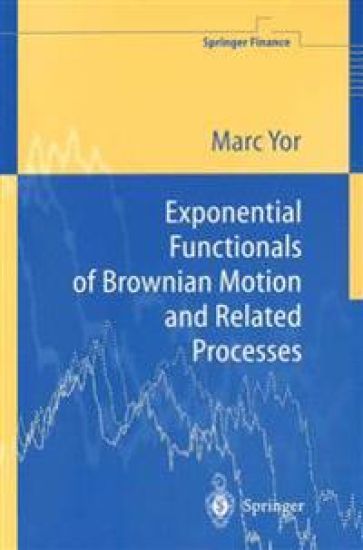
Exponential Functionals of Brownian Motion and Related Processes – hinnat ja saatavuus
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9783540659433 (nidottu).
Kirjan kuvaus
This monograph contains: - ten papers written by the author, and co-authors, between December 1988 and October 1998 about certain exponential functionals of Brownian motion and related processes, which have been, and still are, of… Näytä koko kuvaus Piilota kuvaus
This monograph contains: - ten papers written by the author, and co-authors, between December 1988 and October 1998 about certain exponential functionals of Brownian motion and related processes, which have been, and still are, of interest, during at least the last decade, to researchers in Mathematical finance; - an introduction to the subject from the view point of Mathematical Finance by H. Geman. The origin of my interest in the study of exponentials of Brownian motion in relation with mathematical finance is the question, first asked to me by S. Jacka in Warwick in December 1988, and later by M. Chesney in Geneva, and H. Geman in Paris, to compute the price of Asian options, i. e. : to give, as much as possible, an explicit expression for: (1) where A~v) = I~ dsexp2(Bs + liS), with (Bs,s::::: 0) a real-valued Brownian motion. Since the exponential process of Brownian motion with drift, usually called: geometric Brownian motion, may be represented as: t ::::: 0, (2) where (Rt), u ::::: 0) denotes a 15-dimensional Bessel process, with 5 = 2(1I+1), it seemed clear that, starting from (2) [which is analogous to Feller's repre sentation of a linear diffusion X in terms of Brownian motion, via the scale function and the speed measure of X], it should be possible to compute quan tities related to (1), in particular: in hinging on former computations for Bessel processes.
Kirjan tiedot
Vertaa kirjan ”Exponential Functionals of Brownian Motion and Related Processes” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9783540659433.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
Exponential Functionals of Brownian Motion and Related Processes – hintahistoria
Seuraamme kirjan Exponential Functionals of Brownian Motion and Related Processes hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.