
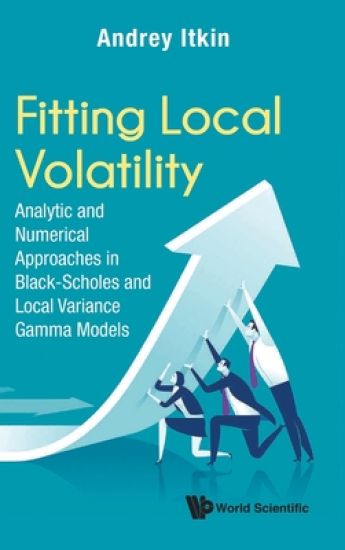
Fitting Local Volatility: Analytic And Numerical Approaches In Black-scholes And Local Variance Gamma Models – hinnat ja saatavuus
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9789811212765 (sidottu).
Kirjan kuvaus
The concept of local volatility as well as the local volatility model are one of the classical topics of mathematical finance. Although the existing literature is wide, there still exist various problems that have not drawn sufficient… Näytä koko kuvaus Piilota kuvaus
The concept of local volatility as well as the local volatility model are one of the classical topics of mathematical finance. Although the existing literature is wide, there still exist various problems that have not drawn sufficient attention so far, for example: a) construction of analytical solutions of the Dupire equation for an arbitrary shape of the local volatility function; b) construction of parametric or non-parametric regression of the local volatility surface suitable for fast calibration; c) no-arbitrage interpolation and extrapolation of the local and implied volatility surfaces; d) extension of the local volatility concept beyond the Black-Scholes model, etc. Also, recent progresses in deep learning and artificial neural networks as applied to financial engineering have made it reasonable to look again at various classical problems of mathematical finance including that of building a no-arbitrage local/implied volatility surface and calibrating it to the option market data. This book was written with the purpose of presenting new results previously developed in a series of papers and explaining them consistently, starting from the general concept of Dupire, Derman and Kani and then concentrating on various extensions proposed by the author and his co-authors. This volume collects all the results in one place, and provides some typical examples of the problems that can be efficiently solved using the proposed methods. This also results in a faster calibration of the local and implied volatility surfaces as compared to standard approaches. The methods and solutions presented in this volume are new and recently published, and are accompanied by various additional comments and considerations. Since from the mathematical point of view, the level of details is closer to the applied rather than to the abstract or pure theoretical mathematics, the book could also be recommended to graduate students with majors in computational or quantitative finance, financial engineering or even applied mathematics. In particular, the author used to teach some topics of this book as a part of his special course on computational finance at the Tandon School of Engineering, New York University.
Kirjan tiedot
Vertaa kirjan ”Fitting Local Volatility: Analytic And Numerical Approaches In Black-scholes And Local Variance Gamma Models” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9789811212765.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
Fitting Local Volatility: Analytic And Numerical Approaches In Black-scholes And Local Variance Gamma Models – hintahistoria
Seuraamme kirjan Fitting Local Volatility: Analytic And Numerical Approaches In Black-scholes And Local Variance Gamma Models hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.