
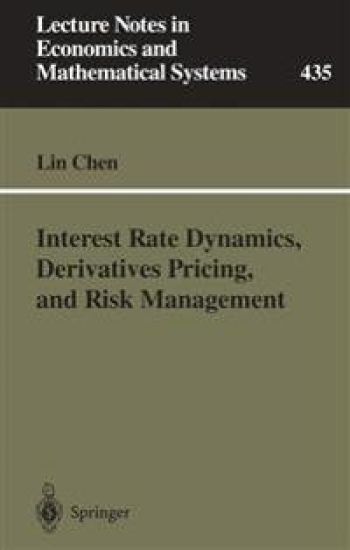
Interest Rate Dynamics, Derivatives Pricing, and Risk Management – hinnat ja saatavuus
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9783540608141 (nidottu).
Kirjan kuvaus
There are two types of tenn structure models in the literature: the equilibrium models and the no-arbitrage models. And there are, correspondingly, two types of interest rate derivatives pricing fonnulas based on each type of model of the… Näytä koko kuvaus Piilota kuvaus
There are two types of tenn structure models in the literature: the equilibrium models and the no-arbitrage models. And there are, correspondingly, two types of interest rate derivatives pricing fonnulas based on each type of model of the tenn structure. The no-arbitrage models are characterized by the work of Ho and Lee (1986), Heath, Jarrow, and Morton (1992), Hull and White (1990 and 1993), and Black, Dennan and Toy (1990). Ho and Lee (1986) invent the no-arbitrage approach to the tenn structure modeling in the sense that the model tenn structure can fit the initial (observed) tenn structure of interest rates. There are a number of disadvantages with their model. First, the model describes the whole volatility structure by a sin gle parameter, implying a number of unrealistic features. Furthennore, the model does not incorporate mean reversion. Black-Dennan-Toy (1990) develop a model along tbe lines of Ho and Lee. They eliminate some of the problems of Ho and Lee (1986) but create a new one: for a certain specification of the volatility function, the short rate can be mean-fteeting rather than mean-reverting. Heath, Jarrow and Morton (1992) (HJM) construct a family of continuous models of the term struc ture consistent with the initial tenn structure data.
Kirjan tiedot
Vertaa kirjan ”Interest Rate Dynamics, Derivatives Pricing, and Risk Management” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9783540608141.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
Interest Rate Dynamics, Derivatives Pricing, and Risk Management – hintahistoria
Seuraamme kirjan Interest Rate Dynamics, Derivatives Pricing, and Risk Management hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.