
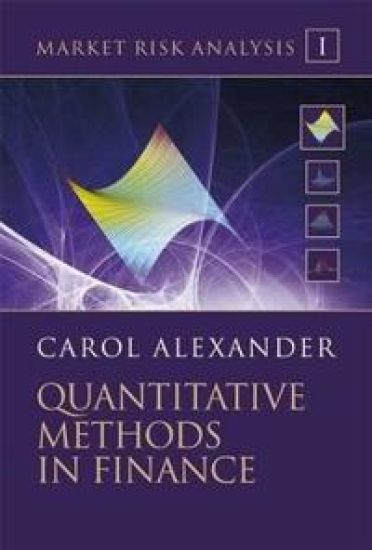
Market Risk Analysis, Quantitative Methods in Finance – hinnat ja saatavuus
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9780470998007 (muu).
Kirjan kuvaus
Written by leading market risk academic, Professor Carol Alexander, Quantitative Methods in Finance forms part one of the Market Risk Analysis four volume set. Starting from the basics, this book helps readers to take the first step… Näytä koko kuvaus Piilota kuvaus
Written by leading market risk academic, Professor Carol Alexander, Quantitative Methods in Finance forms part one of the Market Risk Analysis four volume set. Starting from the basics, this book helps readers to take the first step towards becoming a properly qualified financial risk manager and asset manager, roles that are currently in huge demand. Accessible to intelligent readers with a moderate understanding of mathematics at high school level or to anyone with a university degree in mathematics, physics or engineering, no prior knowledge of finance is necessary. Instead the emphasis is on understanding ideas rather than on mathematical rigour, meaning that this book offers a fast-track introduction to financial analysis for readers with some quantitative background, highlighting those areas of mathematics that are particularly relevant to solving problems in financial risk management and asset management. Unique to this book is a focus on both continuous and discrete time finance so that Quantitative Methods in Finance is not only about the application of mathematics to finance; it also explains, in very pedagogical terms, how the continuous time and discrete time finance disciplines meet, providing a comprehensive, highly accessible guide which will provide readers with the tools to start applying their knowledge immediately. All together, the Market Risk Analysis four volume set illustrates virtually every concept or formula with a practical, numerical example or a longer, empirical case study. Across all four volumes there are approximately 300 numerical and empirical examples, 400 graphs and figures and 30 case studies many of which are contained in interactive Excel spreadsheets available from the accompanying CD-ROM. Empirical examples and case studies specific to this volume include: Principal component analysis of European equity indices;Calibration of Student t distribution by maximum likelihood;Orthogonal regression and estimation of equity factor models;Simulations of geometric Brownian motion, and of correlated Student t variables;Pricing European and American options with binomial trees, and European options with the Black-Scholes-Merton formula;Cubic spline fitting of yields curves and implied volatilities;Solution of Markowitz problem with no short sales and other constraints;Calculation of risk adjusted performance metrics including generalised Sharpe ratio, omega and kappa indices.
Kirjan tiedot
Vertaa kirjan ”Market Risk Analysis, Quantitative Methods in Finance” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9780470998007.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
Market Risk Analysis, Quantitative Methods in Finance – hintahistoria
Seuraamme kirjan Market Risk Analysis, Quantitative Methods in Finance hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.