
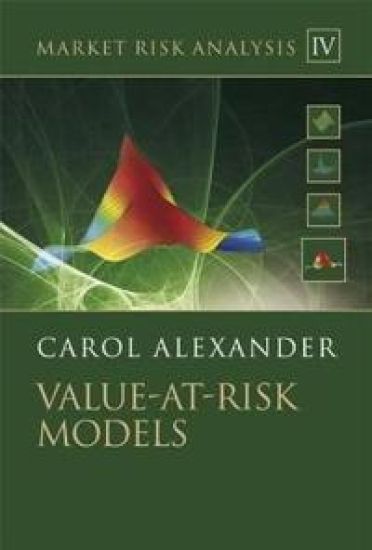
Market Risk Analysis, Value at Risk Models – hinnat ja saatavuus
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9780470997888 (sidottu).
Kirjan kuvaus
Written by leading market risk academic, Professor Carol Alexander, Value-at-Risk Models forms part four of the Market Risk Analysis four volume set. Building on the three previous volumes this book provides by far the most comprehensive,… Näytä koko kuvaus Piilota kuvaus
Written by leading market risk academic, Professor Carol Alexander, Value-at-Risk Models forms part four of the Market Risk Analysis four volume set. Building on the three previous volumes this book provides by far the most comprehensive, rigorous and detailed treatment of market VaR models. It rests on the basic knowledge of financial mathematics and statistics gained from Volume I, of factor models, principal component analysis, statistical models of volatility and correlation and copulas from Volume II and, from Volume III, knowledge of pricing and hedging financial instruments and of mapping portfolios of similar instruments to risk factors. A unifying characteristic of the series is the pedagogical approach to practical examples that are relevant to market risk analysis in practice. All together, the Market Risk Analysis four volume set illustrates virtually every concept or formula with a practical, numerical example or a longer, empirical case study. Across all four volumes there are approximately 300 numerical and empirical examples, 400 graphs and figures and 30 case studies many of which are contained in interactive Excel spreadsheets available from the the accompanying CD-ROM . Empirical examples and case studies specific to this volume include: Parametric linear value at risk (VaR)models: normal, Student t and normal mixture and their expected tail loss (ETL);New formulae for VaR based on autocorrelated returns;Historical simulation VaR models: how to scale historical VaR and volatility adjusted historical VaR;Monte Carlo simulation VaR models based on multivariate normal and Student t distributions, and based on copulas;Examples and case studies of numerous applications to interest rate sensitive, equity, commodity and international portfolios;Decomposition of systematic VaR of large portfolios into standard alone and marginal VaR components;Backtesting and the assessment of risk model risk;Hypothetical factor push and historical stress tests, and stress testing based on VaR and ETL.
Kirjan tiedot
Vertaa kirjan ”Market Risk Analysis, Value at Risk Models” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9780470997888.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
Market Risk Analysis, Value at Risk Models – hintahistoria
Seuraamme kirjan Market Risk Analysis, Value at Risk Models hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.