
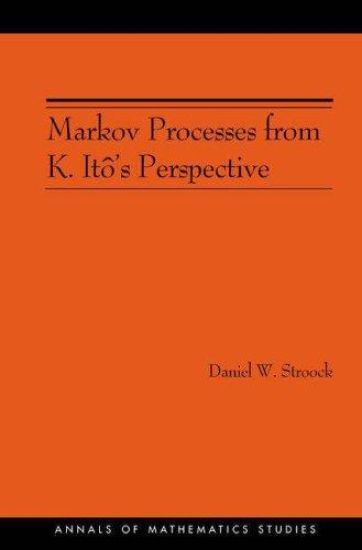
Markov Processes from K. Itô's Perspective – hinnat ja saatavuus
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9780691115436 (pokkari).
Kirjan kuvaus
Kiyosi Ito's greatest contribution to probability theory may be his introduction of stochastic differential equations to explain the Kolmogorov-Feller theory of Markov processes. Starting with the geometric ideas that guided him, this book… Näytä koko kuvaus Piilota kuvaus
Kiyosi Ito's greatest contribution to probability theory may be his introduction of stochastic differential equations to explain the Kolmogorov-Feller theory of Markov processes. Starting with the geometric ideas that guided him, this book gives an account of Ito's program. The modern theory of Markov processes was initiated by A. N. Kolmogorov. However, Kolmogorov's approach was too analytic to reveal the probabilistic foundations on which it rests. In particular, it hides the central role played by the simplest Markov processes: those with independent, identically distributed increments. To remedy this defect, Ito interpreted Kolmogorov's famous forward equation as an equation that describes the integral curve of a vector field on the space of probability measures. Thus, in order to show how Ito's thinking leads to his theory of stochastic integral equations, Stroock begins with an account of integral curves on the space of probability measures and then arrives at stochastic integral equations when he moves to a pathspace setting. In the first half of the book, everything is done in the context of general independent increment processes and without explicit use of Ito's stochastic integral calculus. In the second half, the author provides a systematic development of Ito's theory of stochastic integration: first for Brownian motion and then for continuous martingales. The final chapter presents Stratonovich's variation on Ito's theme and ends with an application to the characterization of the paths on which a diffusion is supported. The book should be accessible to readers who have mastered the essentials of modern probability theory and should provide such readers with a reasonably thorough introduction to continuous-time, stochastic processes.
Kirjan tiedot
Vertaa kirjan ”Markov Processes from K. Itô's Perspective” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9780691115436.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
Markov Processes from K. Itô's Perspective – hintahistoria
Seuraamme kirjan Markov Processes from K. Itô's Perspective hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.