
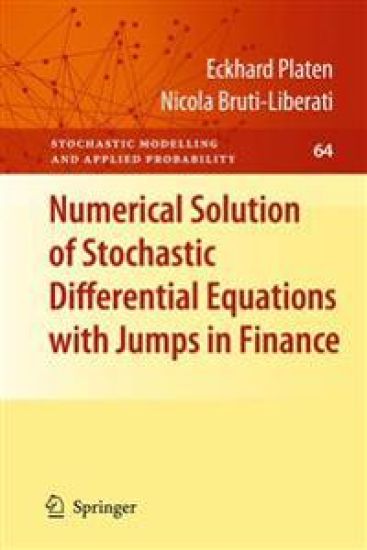
Numerical Solution of Stochastic Differential Equations with Jumps in Finance – hinnat ja saatavuus
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9783662519738 (nidottu).
Muut painokset ja formaatit
Kirjan kuvaus
In financial and actuarial modeling and other areas of application, stochastic differential equations with jumps have been employed to describe the dynamics of various state variables. The numerical solution of such equations is more… Näytä koko kuvaus Piilota kuvaus
In financial and actuarial modeling and other areas of application, stochastic differential equations with jumps have been employed to describe the dynamics of various state variables. The numerical solution of such equations is more complex than that of those only driven by Wiener processes, described in Kloeden & Platen: Numerical Solution of Stochastic Differential Equations (1992). The present monograph builds on the above-mentioned work and provides an introduction to stochastic differential equations with jumps, in both theory and application, emphasizing the numerical methods needed to solve such equations. It presents many new results on higher-order methods for scenario and Monte Carlo simulation, including implicit, predictor corrector, extrapolation, Markov chain and variance reduction methods, stressing the importance of their numerical stability. Furthermore, it includes chapters on exact simulation, estimation and filtering. Besides serving as a basic text on quantitativemethods, it offers ready access to a large number of potential research problems in an area that is widely applicable and rapidly expanding. Finance is chosen as the area of application because much of the recent research on stochastic numerical methods has been driven by challenges in quantitative finance. Moreover, the volume introduces readers to the modern benchmark approach that provides a general framework for modeling in finance and insurance beyond the standard risk-neutral approach. It requires undergraduate background in mathematical or quantitative methods, is accessible to a broad readership, including those who are only seeking numerical recipes, and includes exercises that help the reader develop a deeper understanding of the underlying mathematics.
Kirjan tiedot
Vertaa kirjan ”Numerical Solution of Stochastic Differential Equations with Jumps in Finance” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9783662519738.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
Numerical Solution of Stochastic Differential Equations with Jumps in Finance – hintahistoria
Seuraamme kirjan Numerical Solution of Stochastic Differential Equations with Jumps in Finance hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.