
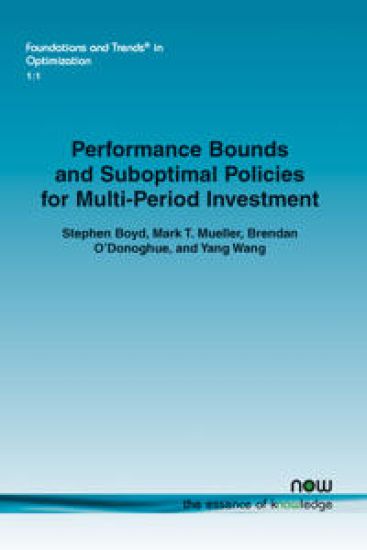
Performance Bounds and Suboptimal Policies for Multi-Period Investment – hinnat ja saatavuus
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9781601986726 (nidottu).
Kirjan kuvaus
Examines dynamic trading of a portfolio of assets in discrete periods over a finite time horizon, with arbitrary time-varying distribution of asset returns. The goal is to maximize the total expected revenue from the portfolio, while… Näytä koko kuvaus Piilota kuvaus
Examines dynamic trading of a portfolio of assets in discrete periods over a finite time horizon, with arbitrary time-varying distribution of asset returns. The goal is to maximize the total expected revenue from the portfolio, while respecting constraints on the portfolio like a required terminal portfolio and leverage and risk limits. The revenue takes into account the gross cash generated in trades, transaction costs, and costs associated with the positions, such as fees for holding short positions. The model that is presented takes the form of a stochastic control problem with linear dynamics and convex cost function and constraints. While this problem can be tractably solved in several special cases - for example, when all costs are convex quadratic, or when there are no transaction costs - the focus is on the more general case, with nonquadratic cost terms and transaction costs. Performance Bounds and Suboptimal Policies for Multi-Period Investment shows how to use linear matrix inequality techniques and semidefinite programming to produce a quadratic bound on the value function, which in turn gives a bound on the optimal performance. This performance bound can be used to judge the performance obtained by any suboptimal policy. As a by-product of the performance bound computation, an approximate dynamic programming policy is obtained that requires the solution of a convex optimization problem, often a quadratic program, to determine the trades to carry out in each step.
Kirjan tiedot
Vertaa kirjan ”Performance Bounds and Suboptimal Policies for Multi-Period Investment” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9781601986726.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
Performance Bounds and Suboptimal Policies for Multi-Period Investment – hintahistoria
Seuraamme kirjan Performance Bounds and Suboptimal Policies for Multi-Period Investment hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.