
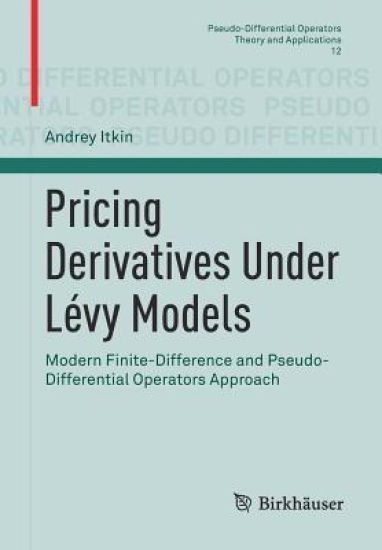
Pricing Derivatives Under Lévy Models – hinnat ja saatavuus
Modern Finite-Difference and Pseudo-Differential Operators Approach
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9781493967902 (nidottu).
Kirjan kuvaus
This monograph presents a novel numerical approach to solving partial integro-differential equations arising in asset pricing models with jumps, which greatly exceeds the efficiency of existing approaches. The method, based on… Näytä koko kuvaus Piilota kuvaus
This monograph presents a novel numerical approach to solving partial integro-differential equations arising in asset pricing models with jumps, which greatly exceeds the efficiency of existing approaches. The method, based on pseudo-differential operators and several original contributions to the theory of finite-difference schemes, is new as applied to the Lévy processes in finance, and is herein presented for the first time in a single volume. The results within, developed in a series of research papers, are collected and arranged together with the necessary background material from Lévy processes, the modern theory of finite-difference schemes, the theory of M-matrices and EM-matrices, etc., thus forming a self-contained work that gives the reader a smooth introduction to the subject. For readers with no knowledge of finance, a short explanation of the main financial terms and notions used in the book is given in the glossary. The latter part of the book demonstrates the efficacy of the method by solving some typical problems encountered in computational finance, including structural default models with jumps, and local stochastic volatility models with stochastic interest rates and jumps. The author also adds extra complexity to the traditional statements of these problems by taking into account jumps in each stochastic component while all jumps are fully correlated, and shows how this setting can be efficiently addressed within the framework of the new method. Written for non-mathematicians, this book will appeal to financial engineers and analysts, econophysicists, and researchers in applied numerical analysis. It can also be used as an advance course on modern finite-difference methods or computational finance.
Kirjan tiedot
Vertaa kirjan ”Pricing Derivatives Under Lévy Models” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9781493967902.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
Pricing Derivatives Under Lévy Models – hintahistoria
Seuraamme kirjan Pricing Derivatives Under Lévy Models hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.