
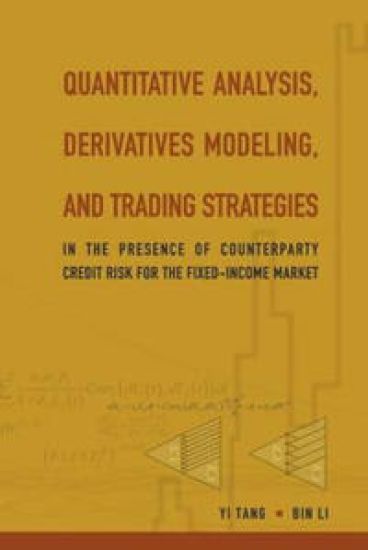
Quantitative Analysis, Derivatives Modeling, And Trading Strategies: In The Presence Of Counterparty Credit Risk For The Fixed-income Market – hinnat ja saatavuus
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9789813203228 (nidottu).
Kirjan kuvaus
This book addresses selected practical applications and recent developments in the areas of quantitative financial modeling in derivatives instruments, some of which are from the authors' own research and practice. It is written from the… Näytä koko kuvaus Piilota kuvaus
This book addresses selected practical applications and recent developments in the areas of quantitative financial modeling in derivatives instruments, some of which are from the authors' own research and practice. It is written from the viewpoint of financial engineers or practitioners, and, as such, it puts more emphasis on the practical applications of financial mathematics in the real market than the mathematics itself with precise (and tedious) technical conditions. It attempts to combine economic insights with mathematics and modeling so as to help the reader to develop intuitions. Among the modeling and the numerical techniques presented are the practical applications of the martingale theories, such as martingale model factory and martingale resampling and interpolation. In addition, the book addresses the counterparty credit risk modeling, pricing, and arbitraging strategies from the perspective of a front office functionality and a revenue center (rather than merely a risk management functionality), which are relatively recent developments and are of increasing importance. It also discusses various trading structuring strategies and touches upon some popular credit/IR/FX hybrid products, such as PRDC, TARN, Snowballs, Snowbears, CCDS, and credit extinguishers. While the primary scope of this book is the fixed-income market (with further focus on the interest rate market), many of the methodologies presented also apply to other financial markets, such as the credit, equity, foreign exchange, and commodity markets.
Kirjan tiedot
Vertaa kirjan ”Quantitative Analysis, Derivatives Modeling, And Trading Strategies: In The Presence Of Counterparty Credit Risk For The Fixed-income Market” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9789813203228.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
Quantitative Analysis, Derivatives Modeling, And Trading Strategies: In The Presence Of Counterparty Credit Risk For The Fixed-income Market – hintahistoria
Seuraamme kirjan Quantitative Analysis, Derivatives Modeling, And Trading Strategies: In The Presence Of Counterparty Credit Risk For The Fixed-income Market hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.