
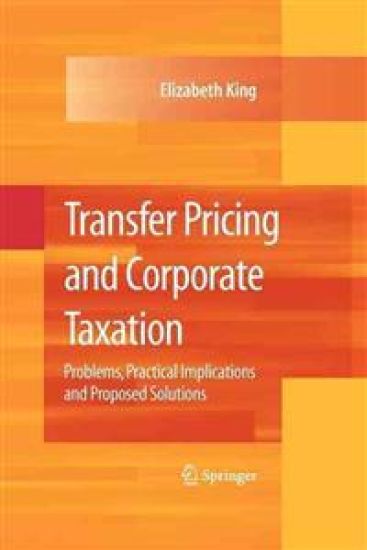
Transfer Pricing and Corporate Taxation – hinnat ja saatavuus
Problems, Practical Implications and Proposed Solutions
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9781441926784 (nidottu).
Muut painokset ja formaatit
Kirjan kuvaus
National tax authorities individually determine multinational ?rms’ country-speci?c tax liabilities by applying one or more sanctioned transfer pricing methodologies. These methodologies are founded on basic assumptions about market… Näytä koko kuvaus Piilota kuvaus
National tax authorities individually determine multinational ?rms’ country-speci?c tax liabilities by applying one or more sanctioned transfer pricing methodologies. These methodologies are founded on basic assumptions about market structure and ?rm behavior that are rarely empirically valid. Moreover, for the most part, the transfer pricing methodologies now in vogue were developed before the Internet became a dominant factor in the world economy, and hedge and private equity funds transformed ?nancial and commodities markets. For these reasons, multinational ?rms are unable to accurately anticipate their tax liabilities in individual countries, and remain at risk of double taxation. Uncertainties in corporate tax liability are extremely costly, both for individual corporations and from an economy-wide perspective. Firms pay exorbitant fees to have tax attorneys, accountants and economists prepare the documentation required by tax authorities to substantiate their intercompany pricing practices and defend their tax positions on audit. Corporate tax liabilities are also potentially much higher than they would be under a more transparent and predictable transfer pricing regime (due to the potential for double taxation and penalties), and investors’ returns are reduced accordingly. The FASB’s Interpretation No. 48, Accounting for Uncertainty in Income Taxes (released on July 13, 2006), has motivated multinational ?rms to increase their reserves substantially (in many cases at the insistence of their au- tors), reducing the total funds available for productive investment. 1 The current transfer pricing regimes are embodied in the OECD Guidelines, individual OECD member countries’ interpretations thereof, the U. S.
Kirjan tiedot
Vertaa kirjan ”Transfer Pricing and Corporate Taxation” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9781441926784.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
Transfer Pricing and Corporate Taxation – hintahistoria
Seuraamme kirjan Transfer Pricing and Corporate Taxation hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.