Kirjojen hintavertailu – 12 859 818 kirjaa ja 27 kauppaa
Kirjailija
Tomas Björk
Kirjat ja teokset yhdessä paikassa: 9 kirjaa, julkaisuja vuosilta 2004–2022, suosituimpiin kuuluu Prins Eugen : fasetter ur ett liv. Vertaile teosten hintoja ja tarkista saatavuus suomalaisista kirjakaupoista.
Anna Meister; Karin Sidén; Tomas Björk; Hans Henrik Brummer; Per I. Gedin; Anders Hammarlund; Mats Myrstener; Marina Rydberg; Martin Rörby; Elsebeth Welander-Berggren; Christina G. Wistam
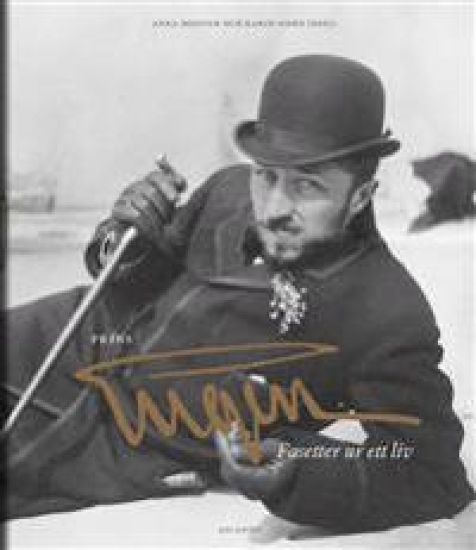
I Prins Eugen - Fasetter ur ett liv, som ges ut i samband med den stora jubileumsutställningen på Waldemarsudde, tecknas för första gången en helhetsbild av personen och människan Prins Eugen och hans livsgärning. Han var inte bara konstnär, formgivare och konstsamlare utan också kulturpolitiker, folkbildare och musikkännare. Även hemmet på Waldemarsudde presenteras i text och bild.
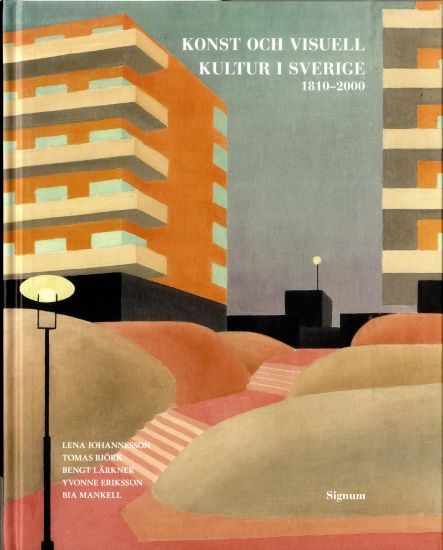
En ny sammanfattande svensk konsthistoria har varit efterlängtad. Med denna andra del av Konst och visuell kultur i Sverige fylls denna lucka. Vi får här följa den svenska konstens utveckling under två århundraden präglade av modernitet och mestadels stark framtidstro. Framväxten av konstriktningar som kubism, surrealism och konkretism behandlas utförligt, liksom arkitekturens utveckling från historisk stileklekticism över jugend, nationalromantik och funktionalism till postmodernismens nya eklekticism. Andra ämnen är uppkomsten av massproducerade bilder, genombrottet för fotografi och industridesign och kvinnornas plats i konsten. Omprövning och uppdatering har varit självklara ledstjärnor för författarna. Nytt är att hela den visuella kultur, som vi människor lever i, behandlas.
Karin Sidén; Anna Meister; Christina G. Wistman; Hans Henrik Brummer; Tomas Björk; Mats Myrstener; Per I Gedin; Martin Rörby; Elsebeth Welander-Berggren; Martina Rydberg; Anders Hammarlund
2015 är det 150 år sedan Prins Eugen (1865-1947) föddes. Prins Eugens Waldemarsudde firar detta med en stor jubileumsutställning och bok om prinsen och hans livsgärning. Här ges en ingående presentation av prinsen som person och hans olika engagemang som kulturpolitiker och folkbildare, liksom hans politiska ställningstaganden.
The Paris-Princeton Lectures in Financial Mathematics, of which this is the second volume, will, on an annual basis, publish cutting-edge research in self-contained, expository articles from outstanding - established or upcoming! - specialists. The aim is to produce a series of articles that can serve as an introductory reference for research in the field. It arises as a result of frequent exchanges between the finance and financial mathematics groups in Paris and Princeton. This volume presents the following articles: "Hedging of Defaultable Claims" by T. Bielecki, M. Jeanblanc, and M. Rutkowski; "On the Geometry of Interest Rate Models" by T. Björk; "Heterogeneous Beliefs, Speculation and Trading in Financial Markets" by J. A. Scheinkman, and W. Xiong.
This book is devoted to problems of stochastic control and stopping that are time inconsistent in the sense that they do not admit a Bellman optimality principle. These problems are cast in a game-theoretic framework, with the focus on subgame-perfect Nash equilibrium strategies. The general theory is illustrated with a number of finance applications. In dynamic choice problems, time inconsistency is the rule rather than the exception. Indeed, as Robert H. Strotz pointed out in his seminal 1955 paper, relaxing the widely used ad hoc assumption of exponential discounting gives rise to time inconsistency. Other famous examples of time inconsistency include mean-variance portfolio choice and prospect theory in a dynamic context. For such models, the very concept of optimality becomes problematic, as the decision maker’s preferences change over time in a temporally inconsistent way. In this book, a time-inconsistent problem is viewed as a non-cooperative game between the agent’s currentand future selves, with the objective of finding intrapersonal equilibria in the game-theoretic sense. A range of finance applications are provided, including problems with non-exponential discounting, mean-variance objective, time-inconsistent linear quadratic regulator, probability distortion, and market equilibrium with time-inconsistent preferences. Time-Inconsistent Control Theory with Finance Applications offers the first comprehensive treatment of time-inconsistent control and stopping problems, in both continuous and discrete time, and in the context of finance applications. Intended for researchers and graduate students in the fields of finance and economics, it includes a review of the standard time-consistent results, bibliographical notes, as well as detailed examples showcasing time inconsistency problems. For the reader unacquainted with standard arbitrage theory, an appendix provides a toolbox of material needed for the book.
This book is devoted to problems of stochastic control and stopping that are time inconsistent in the sense that they do not admit a Bellman optimality principle. These problems are cast in a game-theoretic framework, with the focus on subgame-perfect Nash equilibrium strategies. The general theory is illustrated with a number of finance applications. In dynamic choice problems, time inconsistency is the rule rather than the exception. Indeed, as Robert H. Strotz pointed out in his seminal 1955 paper, relaxing the widely used ad hoc assumption of exponential discounting gives rise to time inconsistency. Other famous examples of time inconsistency include mean-variance portfolio choice and prospect theory in a dynamic context. For such models, the very concept of optimality becomes problematic, as the decision maker’s preferences change over time in a temporally inconsistent way. In this book, a time-inconsistent problem is viewed as a non-cooperative game between the agent’s currentand future selves, with the objective of finding intrapersonal equilibria in the game-theoretic sense. A range of finance applications are provided, including problems with non-exponential discounting, mean-variance objective, time-inconsistent linear quadratic regulator, probability distortion, and market equilibrium with time-inconsistent preferences. Time-Inconsistent Control Theory with Finance Applications offers the first comprehensive treatment of time-inconsistent control and stopping problems, in both continuous and discrete time, and in the context of finance applications. Intended for researchers and graduate students in the fields of finance and economics, it includes a review of the standard time-consistent results, bibliographical notes, as well as detailed examples showcasing time inconsistency problems. For the reader unacquainted with standard arbitrage theory, an appendix provides a toolbox of material needed for the book.
The theory of marked point processes on the real line is of great and increasing importance in areas such as insurance mathematics, queuing theory and financial economics. However, the theory is often viewed as technically and conceptually difficult and has proved to be a block for PhD students looking to enter the area. This book gives an intuitive picture of the central concepts as well as the deeper results, while presenting the mathematical theory in a rigorous fashion and discussing applications in filtering theory and financial economics. Consequently, readers will get a deep understanding of the theory and how to use it. A number of exercises of differing levels of difficulty are included, providing opportunities to put new ideas into practice. Graduate students in mathematics, finance and economics will gain a good working knowledge of point-process theory, allowing them to progress to independent research.
I den nordiska konsten kring sekelskiftet 1900 utgör magisk besjälad natur en fascinerande och återkommande tematik. Djupa skogar, dimhöljda ängar och brusande forsar, kom i flera verk från denna tid att befolkas av olika naturväsen såsom troll, älvor och Näcken. Intresset för nordisk folktro och mytologi bland bildkonstnärer, sammanföll i tid med nationella strömningar, inflytanden från symbolismens tankevärld och ett uppsving för nedtecknade sägner och illustrerad sagolitteratur. John Bauers fängslande sagoillustrationer presenteras i denna bok i dialog med verk av hans samtida nordiska konstnärskollegor, däribland J. A. G. Acke, Agnes de Frumerie, Akseli Gallen-Kallela, Ernst Josephson, Theodor Kittelsen, Louis Moe och Hugo Simberg. Angelägna frågeställningar, kopplade till natur, magi och identitet, tematiseras inom den nordiska samtidskonsten hos konstnärer såsom Maria Friberg, Elisabeth Henriksson och Tori Wrånes. Denna rikt illustrerade publikation har tillkommit i samband med den omfattande utställningen Trollbunden – John Bauer och den magiska naturen, som visas på Prins Eugens Waldemarsudde hösten 2020 och vintern 2021. Ett antal framstående experter inom konst, litteratur och etnologi ger intressanta perspektiv på folktro och väsen i nordisk konst, sägner och sagor och på visualiseringen av en besjälad natur då och nu.
The fourth edition of this widely used textbook on pricing and hedging of financial derivatives now also includes dynamic equilibrium theory and continues to combine sound mathematical principles with economic applications. Concentrating on the probabilistic theory of continuous time arbitrage pricing of financial derivatives, including stochastic optimal control theory and optimal stopping theory, Arbitrage Theory in Continuous Time is designed for graduate students in economics and mathematics, and combines the necessary mathematical background with a solid economic focus. It includes a solved example for every new technique presented, contains numerous exercises, and suggests further reading in each chapter. All concepts and ideas are discussed, not only from a mathematics point of view, but with lots of intuitive economic arguments. In the substantially extended fourth edition Tomas Björk has added completely new chapters on incomplete markets, treating such topics as the Esscher transform, the minimal martingale measure, f-divergences, optimal investment theory for incomplete markets, and good deal bounds. This edition includes an entirely new section presenting dynamic equilibrium theory, covering unit net supply endowments models and the Cox-Ingersoll-Ross equilibrium factor model. Providing two full treatments of arbitrage theory-the classical delta hedging approach and the modern martingale approach-this book is written so that these approaches can be studied independently of each other, thus providing the less mathematically-oriented reader with a self-contained introduction to arbitrage theory and equilibrium theory, while at the same time allowing the more advanced student to see the full theory in action. This textbook is a natural choice for graduate students and advanced undergraduates studying finance and an invaluable introduction to mathematical finance for mathematicians and professionals in the market.