
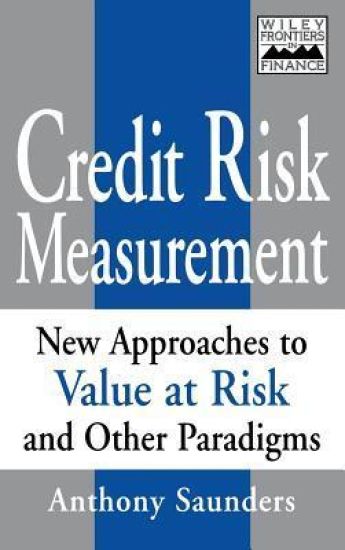
Credit Risk Measurement – hinnat ja saatavuus
New Approaches to Value-at-Risk and Other Paradigms
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9780471350842 (sidottu).
Kirjan kuvaus
The single most important topic in finance today is the art and science of credit risk management. Growing dissatisfaction with traditional credit risk measurement methods has combined with regulations imposed by the Bank for International… Näytä koko kuvaus Piilota kuvaus
The single most important topic in finance today is the art and science of credit risk management. Growing dissatisfaction with traditional credit risk measurement methods has combined with regulations imposed by the Bank for International Settlements (BIS) in 1993 to send numerous financial institutions in search of alternative "internal model" approaches to measuring the credit risk of a loan or portfolio of loans. This has led to a raging debate over whether internal models can replace regulatory models, and which areas of credit risk measurement and management are most amenable to internal models. Much of this highly technical debate, however, has been inaccessible to the interested practitioner, student, economist, or regulator-until now. In Credit Risk Measurement: New Approaches to Value at Risk and Other Paradigms, Anthony Saunders invites a wider audience into the debate. Simplifying many of the technical details and analytics surrounding internal models, he concentrates on their underlying economics and economic intuition. Professor Saunders examines the approaches of these new models to the evaluation of individual borrower credit risk, portfolio credit risk, and derivative contracts. The alternative models explored include: * Loans as options and the KMV model * The VAR approach: J. P. Morgan's CreditMetrics and other models * The macro simulation approach: the McKinsey and other models * The risk-neutral valuation approach: KPMG's Loan Analysis System (LAS) and other models * The insurance approach: mortality models and CSFP credit risk plus model * Back testing and stress testing credit risk models * RAROC models With its comprehensive coverage, summary, and comparison of new internal model approaches along with clear explanations of often complex material, Credit Risk Measurement is an indispensable resource for bankers, academics and students, economists, and regulators.
Kirjan tiedot
Vertaa kirjan ”Credit Risk Measurement” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9780471350842.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
Credit Risk Measurement – hintahistoria
Seuraamme kirjan Credit Risk Measurement hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.