
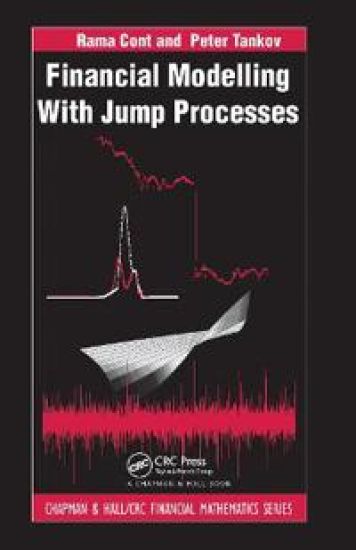
Financial Modelling with Jump Processes – hinnat ja saatavuus
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9781584884132 (sidottu).
Kirjan kuvaus
WINNER of a Riskbook.com Best of 2004 Book Award! During the last decade, financial models based on jump processes have acquired increasing popularity in risk management and option pricing. Much has been published on the subject, but the… Näytä koko kuvaus Piilota kuvaus
WINNER of a Riskbook.com Best of 2004 Book Award! During the last decade, financial models based on jump processes have acquired increasing popularity in risk management and option pricing. Much has been published on the subject, but the technical nature of most papers makes them difficult for nonspecialists to understand, and the mathematical tools required for applications can be intimidating. Potential users often get the impression that jump and Lévy processes are beyond their reach. Financial Modelling with Jump Processes shows that this is not so. It provides a self-contained overview of the theoretical, numerical, and empirical aspects involved in using jump processes in financial modelling, and it does so in terms within the grasp of nonspecialists. The introduction of new mathematical tools is motivated by their use in the modelling process, and precise mathematical statements of results are accompanied by intuitive explanations. Topics covered in this book include: jump-diffusion models, Lévy processes, stochastic calculus for jump processes, pricing and hedging in incomplete markets, implied volatility smiles, time-inhomogeneous jump processes and stochastic volatility models with jumps. The authors illustrate the mathematical concepts with many numerical and empirical examples and provide the details of numerical implementation of pricing and calibration algorithms. This book demonstrates that the concepts and tools necessary for understanding and implementing models with jumps can be more intuitive that those involved in the Black Scholes and diffusion models. If you have even a basic familiarity with quantitative methods in finance, Financial Modelling with Jump Processes will give you a valuable new set of tools for modelling market fluctuations.
Kirjan tiedot
Vertaa kirjan ”Financial Modelling with Jump Processes” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9781584884132.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
Financial Modelling with Jump Processes – hintahistoria
Seuraamme kirjan Financial Modelling with Jump Processes hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.