
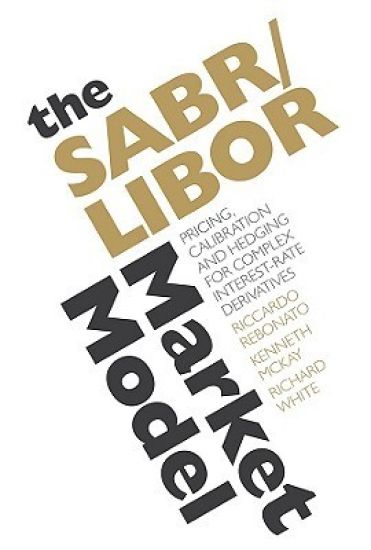
The SABR/LIBOR Market Model – hinnat ja saatavuus
Pricing, Calibration and Hedging for Complex Interest-Rate Derivatives
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9780470740057 (sidottu).
Kirjan kuvaus
This book presents a major innovation in the interest rate space. It explains a financially motivated extension of the LIBOR Market model which accurately reproduces the prices for plain vanilla hedging instruments (swaptions and caplets)… Näytä koko kuvaus Piilota kuvaus
This book presents a major innovation in the interest rate space. It explains a financially motivated extension of the LIBOR Market model which accurately reproduces the prices for plain vanilla hedging instruments (swaptions and caplets) of all strikes and maturities produced by the SABR model. The authors show how to accurately recover the whole of the SABR smile surface using their extension of the LIBOR market model. This is not just a new model, this is a new way of option pricing that takes into account the need to calibrate as accurately as possible to the plain vanilla reference hedging instruments and the need to obtain prices and hedges in reasonable time whilst reproducing a realistic future evolution of the smile surface. It removes the hard choice between accuracy and time because the framework that the authors provide reproduces today's market prices of plain vanilla options almost exactly and simultaneously gives a reasonable future evolution for the smile surface. The authors take the SABR model as the starting point for their extension of the LMM because it is a good model for European options. The problem, however with SABR is that it treats each European option in isolation and the processes for the various underlyings (forward and swap rates) do not talk to each other so it isn't obvious how to relate these processes into the dynamics of the whole yield curve. With this new model, the authors bring the dynamics of the various forward rates and stochastic volatilities under a single umbrella. To ensure the absence of arbitrage they derive drift adjustments to be applied to both the forward rates and their volatilities. When this is completed, complex derivatives that depend on the joint realisation of all relevant forward rates can now be priced. Contents THE THEORETICAL SET-UP The Libor Market model The SABR Model The LMM-SABR Model IMPLEMENTATION AND CALIBRATION Calibrating the LMM-SABR model to Market Caplet prices Calibrating the LMM/SABR model to Market Swaption Prices Calibrating the Correlation Structure EMPIRICAL EVIDENCE The Empirical problem Estimating the volatility of the forward rates Estimating the correlation structure Estimating the volatility of the volatility HEDGING Hedging the Volatility Structure Hedging the Correlation Structure Hedging in conditions of market stress
Kirjan tiedot
Vertaa kirjan ”The SABR/LIBOR Market Model” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9780470740057.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
The SABR/LIBOR Market Model – hintahistoria
Seuraamme kirjan The SABR/LIBOR Market Model hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.