
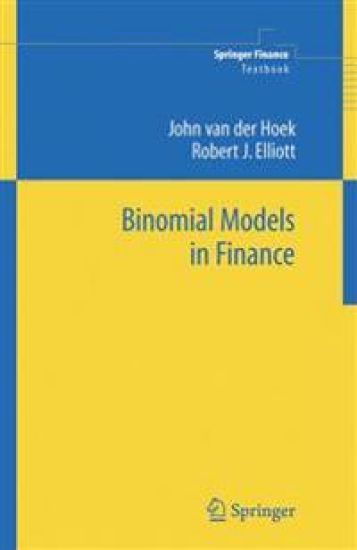
Binomial Models in Finance – hinnat ja saatavuus
Kirjafiili on kirjojen hintavertailu. Löydä halvin hinta 27 kirjakaupasta. Hintavertailu koskee ISBN-tunnusta 9780387258980 (sidottu).
Muut painokset ja formaatit
Kirjan kuvaus
This book describes the modelling of prices of ?nancial assets in a simple d- crete time, discrete state, binomial framework. By avoiding the mathematical technicalitiesofcontinuoustime?nancewehopewehavemadethematerial accessible to a wide… Näytä koko kuvaus Piilota kuvaus
This book describes the modelling of prices of ?nancial assets in a simple d- crete time, discrete state, binomial framework. By avoiding the mathematical technicalitiesofcontinuoustime?nancewehopewehavemadethematerial accessible to a wide audience. Some of the developments and formulae appear here for the ?rst time in book form. We hope our book will appeal to various audiences. These include MBA s- dents,upperlevelundergraduatestudents,beginningdoctoralstudents,qu- titative analysts at a basic level and senior executives who seek material on new developments in ?nance at an accessible level. The basic building block in our book is the one-step binomial model where a known price today can take one of two possible values at a future time, which might, for example, be tomorrow, or next month, or next year. In this simple situation “risk neutral pricing” can be de?ned and the model can be applied to price forward contracts, exchange rate contracts and interest rate derivatives. In a few places we discuss multinomial models to explain the notions of incomplete markets and how pricing can be viewed in such a context, where unique prices are no longer available. The simple one-period framework can then be extended to multi-period m- els. TheCox-Ross-RubinsteinapproximationtotheBlackScholesoptionpr- ing formula is an immediate consequence. American, barrier and exotic - tions can all be discussed and priced using binomial models. More precise modelling issues such as implied volatility trees and implied binomial trees are treated, as well as interest rate models like those due to Ho and Lee; and Black, Derman and Toy.
Kirjan tiedot
Vertaa kirjan ”Binomial Models in Finance” hintoja
Vertaa tuotteen hintaa ja arvioitua kokonaishintaa toimitettuna. Kaikki hinnat koskevat ISBN-tunnusta 9780387258980.
Hintoja ei päivitetty automaattisesti. Voit hakea ajantasaiset hinnat painamalla Hae hinnat.

Booky

Suomalainen

Kansallinen Kirjakauppa

Prisma

Finlandia Kirja

Fantasiapelit

Vinhan kirjakauppa

CDON

Kustantamo S&S
Kennys.ie

Kristillinenkirjakauppa.fi
Sacrum

Adlibris

BookOutlet.fi

Kirja.fi

Rosebud
Tälle kirjalle ei ole tällä hetkellä vahvistettua hintaa. Tarkista tilanne myöhemmin uudelleen.
Hintoja ei ole vielä päivitetty.
Hälytys tallennettu!
Ilmoitamme, kun hinta laskee.
Saat sähköpostin, kun hinta laskee asettamaasi rajaan tai sen alle.
Binomial Models in Finance – hintahistoria
Seuraamme kirjan Binomial Models in Finance hintakehitystä kirjakaupoissa. Taulukosta näet viime kuukausien alimmat hinnat.
Alin hinta kauppoittain
Kunkin kaupan alin hinta viimeisten 90 päivän aikana.
Hintahistoriaa ei ole vielä kerätty tälle kirjalle.
Hinnat ilman toimituskuluja.